Your 401(k) Is Getting a Crypto Upgrade — Whether You're Ready or Not
For most of the past decade, the message from mainstream financial institutions was unambiguous: crypto had no place in a retirement account. Brokerages blocked Bitcoin purchases in IRAs, plan administrators cited regulatory risk, and fiduciary advisors steered clients toward index funds with the conviction of people guarding a vault.
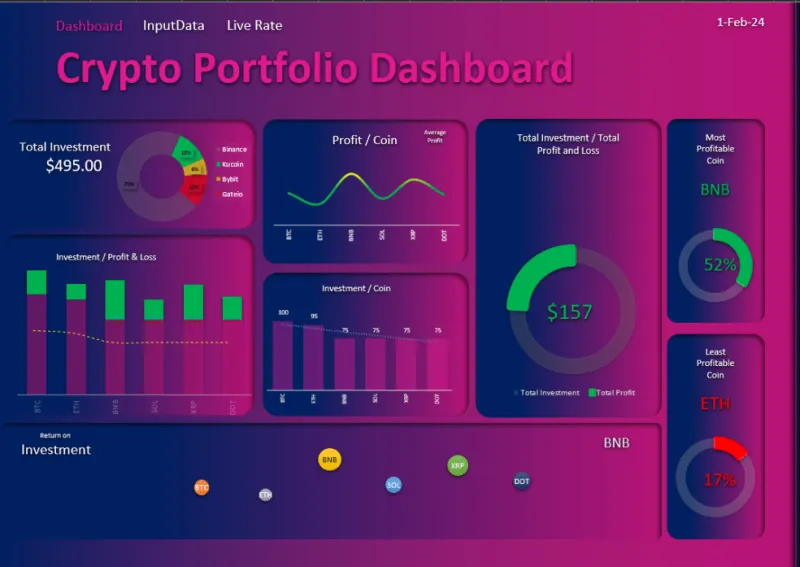
That wall is cracking. Wealth management platforms, robo-advisors, and even some workplace retirement providers are now testing what the industry calls a crypto sleeve — a small, often AI-managed allocation to digital assets inside accounts that were once strictly traditional. The pitch sounds harmless enough: 1% to 5% of your portfolio, handled by an algorithm, with exposure to the upside of an asset class that no longer wants to be ignored.
But the arrival of AI-driven crypto allocations inside American retirement infrastructure raises questions that deserve scrutiny before enrollment buttons get clicked.
How We Got Here
The shift has been incremental. First came Bitcoin futures ETFs, which gave registered advisors a compliant wrapper. Then spot ETFs in early 2024 opened the door to direct-ish exposure without custody headaches. Robo-advisors, which already automate asset allocation using models, found the leap to AI-assisted crypto rebalancing surprisingly short.
The logic is seductive for plan sponsors and wealth managers alike. Digital assets have matured institutionally. AI tools can, in theory, manage volatility better than a nervous human advisor fielding angry calls during a 30% drawdown. And clients — particularly younger ones — keep asking.
The Fiduciary Gray Zone
Here's where it gets uncomfortable. Under ERISA, anyone managing 401(k) assets owes a fiduciary duty: act solely in the interest of participants, keep fees reasonable, and diversify prudently. Whether an AI-managed crypto sleeve satisfies that standard remains largely untested.
Consider the questions regulators have not fully answered:
- Who is liable when the model fails? If an AI system rotates into an altcoin that collapses 80% in a week, does responsibility fall on the platform, the model vendor, or the plan sponsor who approved the option?
- What does "prudent" mean for an algorithmic strategy? DOL guidance on crypto in retirement plans has been cautious at best, and AI management adds another layer of opacity.
- How transparent is the model itself? Fiduciary duty presumes the manager can explain decisions. Machine learning systems that can't articulate why they exited a position complicate that presumption considerably.
The SEC's evolving stance on AI-washing — firms overstating their use of artificial intelligence — suggests regulators are watching, but enforcement trails innovation in this market by years.
What the Marketing Won't Emphasize
The term "smart crypto sleeve" does a lot of work. Smart implies the AI will dodge the crashes. Sleeve implies it's contained, a garnish rather than a meal.
Both framings deserve skepticism. AI trading models in crypto have a documented history of failing in ways their backtests never predicted — from liquidity traps in thin altcoin markets to cascading liquidations during correlated sell-offs. A 3% allocation sounds trivial until you consider that crypto's worst drawdowns have historically coincided with recessions, precisely when the rest of a retirement portfolio is also bleeding.
There's also the fee question. Crypto sleeves tend to carry expense ratios and management fees well above what participants pay for core index funds. Compounded over decades, that difference quietly erodes the very returns the allocation promises to enhance.
Five Questions to Ask Before You Opt In
If your workplace plan or advisory platform rolls out an AI-managed crypto option, treat it like any other investment decision — with a checklist:
- What exactly does the AI do? Rebalance periodically? Trade actively? Select individual tokens? The risk profiles are wildly different.
- What is the total cost, including trading spreads? Crypto transaction costs can hide inside execution, not just the stated fee.
- What's the track record through a full bear market? Bull-market performance is marketing; cycle-tested performance is evidence.
- Who bears fiduciary responsibility? Get the answer in writing.
- Can you replicate the exposure more cheaply? A low-cost spot Bitcoin ETF with periodic rebalancing may capture most of the benefit without the algorithmic black box.
A Reasonable Middle Ground
None of this means AI-managed crypto allocations are a scam. The technology is genuinely improving, and measured exposure to digital assets inside a diversified portfolio is a defensible position for many American investors — particularly those with long time horizons. AI tools that manage position sizing, detect abnormal market conditions, and remove emotional decision-making address real failures of human investing.
The concern is narrower: mainstreaming tends to outpace diligence. When an option arrives pre-approved inside a 401(k) menu, many participants will assume someone else has done the vetting. Sometimes they will have. Sometimes the vetting will have amounted to a vendor's sales deck and a committee meeting.
The mainstreaming of AI-driven crypto is no longer a prediction; it's a rollout in progress. The investors who benefit will be the ones who read the enrollment materials as carefully as the marketing hopes they won't — and who remember that in personal finance, as in markets, the most dangerous phrase is always the same: this time, the algorithm has it handled.